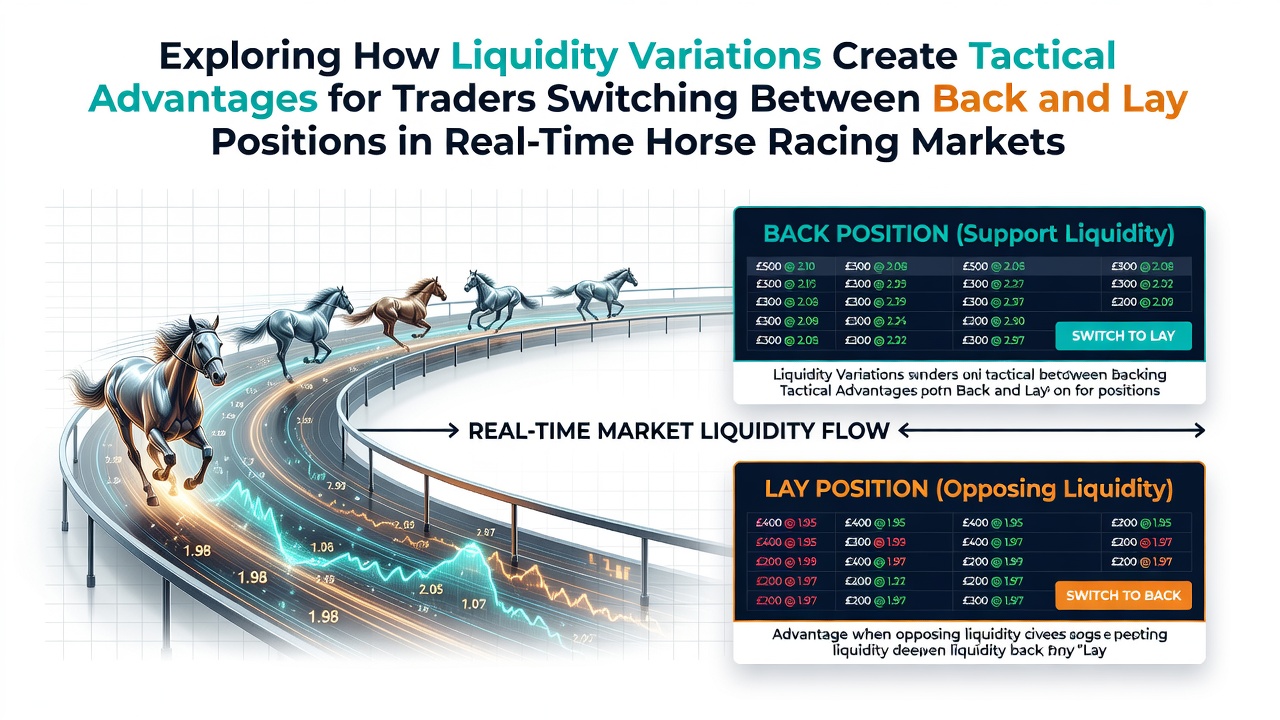
Liquidity Variations Fueling Strategic Back and Lay Adjustments in Live Horse Racing Exchange Environments
Market participants have long tracked how changes in available volume at different price levels influence the ability to move between backing and laying horses during live races, and data from July 2026 shows these patterns persisted across major Australian and North American tracks where exchange activity reached notable peaks during afternoon and evening cards. Observers note that liquidity often clusters around opening odds before thinning in specific bands as the race approaches the start, creating windows where traders can reverse exposure without excessive slippage.
Depth Patterns in Equine Pools
Exchange platforms record order book snapshots that reveal layers of unmatched volume sitting at incremental ticks, and researchers who analyzed tick-by-tick records from multiple July 2026 meetings found that larger pools formed around favorites while mid-range horses experienced thinner bands that widened or contracted within seconds of new information entering the market. When a sudden influx of lay orders arrives at a particular price, the visible depth on the back side shrinks, prompting some participants to close or flip positions before the imbalance corrects itself through subsequent matching. Those who monitor these shifts in real time can identify moments when the cost of switching decreases because resting orders absorb the reversal without moving the traded price far from the entry level.
Timing Reversals Around Liquidity Surges
Volume spikes frequently coincide with race updates such as non-runners, track condition changes, or late jockey announcements, and figures from several North American tracks in July 2026 indicate that these events produced measurable increases in matched volume within narrow timeframes. Traders who maintain automated alerts for depth changes can respond by placing opposing orders that take advantage of the temporary widening of the spread or the appearance of new resting liquidity at favorable levels. Because horse racing markets operate on short time horizons compared with other sports, the window for executing a clean reversal often lasts only a few seconds, making rapid assessment of available depth essential for minimizing execution risk.
Studies conducted by academic teams at institutions focused on financial market microstructure have documented similar behaviors in other limit-order environments, and the same principles apply when horse racing exchanges display clustered orders that create temporary barriers or gaps. In one documented sequence from a July 2026 Australian meeting, liquidity on the lay side of a mid-priced runner expanded rapidly after a track bias report circulated, allowing several accounts to switch from back to lay positions at prices that remained stable for multiple seconds before the order book rebalanced. Such episodes illustrate how depth variations directly affect the feasibility and cost of position changes rather than depending on directional price movement alone.
Order Flow and Position Management
Real-time feeds supplied by exchange operators allow participants to observe the rate at which new orders arrive and cancel, and data compiled across multiple jurisdictions shows that cancellation rates tend to rise when liquidity thins near the off, increasing the chance that a reversal order will cross the spread. Those monitoring cumulative volume deltas can detect when one side of the book begins to dominate, which sometimes precedes a shift in matched prices that favors completing the switch at a net positive outcome. In July 2026 sessions at several European tracks, the pattern repeated during twilight racing cards where reduced overall participation left pockets of depth that responded sharply to small order flow changes.
Regulatory filings from bodies such as the Australian Treasury and reports issued by the International Association of Gaming Regulators confirm that exchange operators must maintain audit trails of order submissions and cancellations, providing researchers with granular datasets that support analysis of liquidity-driven tactics. These records demonstrate that successful reversals often occur when traders align their actions with existing unmatched volume rather than attempting to create new depth in thin segments of the book.
Geographic and Temporal Variations
Liquidity characteristics differ between daytime and evening meetings, between turf and synthetic surfaces, and between jurisdictions with varying participant bases, and July 2026 data highlighted how Australian winter carnivals produced deeper books on feature races while smaller North American tracks showed more pronounced gaps that closed and reopened within minutes. Participants who follow multiple markets simultaneously can route reversals toward the venue where depth supports the intended switch at lower cost, a practice that relies on continuous comparison of available volume across parallel events. Observers note that these cross-market comparisons become particularly relevant during overlapping race times when capital can be redeployed quickly once one position closes and another opens.
Practical Execution Considerations
Platform interfaces display best available prices and quantities, yet the full order book depth remains visible only to logged-in users who request it, and latency between data receipt and order transmission can determine whether a planned reversal executes at the intended level. In periods of elevated activity such as those recorded in July 2026, some exchanges introduced temporary throttling mechanisms that slowed order acceptance when message rates exceeded thresholds, an operational detail that further underscores the need to anticipate liquidity shifts rather than react after they appear. Traders who incorporate historical depth profiles for specific horses or race types into their decision models can better estimate the probability that sufficient volume will remain available when the switch is attempted.
Conclusion
Analysis of exchange data continues to show that liquidity variations create measurable differences in the ease and cost of moving between back and lay positions in real-time horse racing markets, and the patterns observed during July 2026 events align with earlier findings across multiple jurisdictions. Market participants who track depth layers, volume arrival rates, and cancellation activity gain visibility into the conditions that support or hinder tactical reversals, while platform design and regulatory record-keeping requirements supply the raw information needed for ongoing study. These dynamics remain central to how order flow interacts with available liquidity on equine betting exchanges.