Evening Racing Liquidity Layers: Spotting Multi-Level Opportunities on Betting Exchanges
Evening horse racing meetings present distinct market structures where liquidity metrics reveal multiple layers of opportunity for participants tracking order flow and depth indicators on betting exchanges, and data from July 2026 shows increased participation in these sessions across several jurisdictions as traders monitor volume clusters that form before and during races.
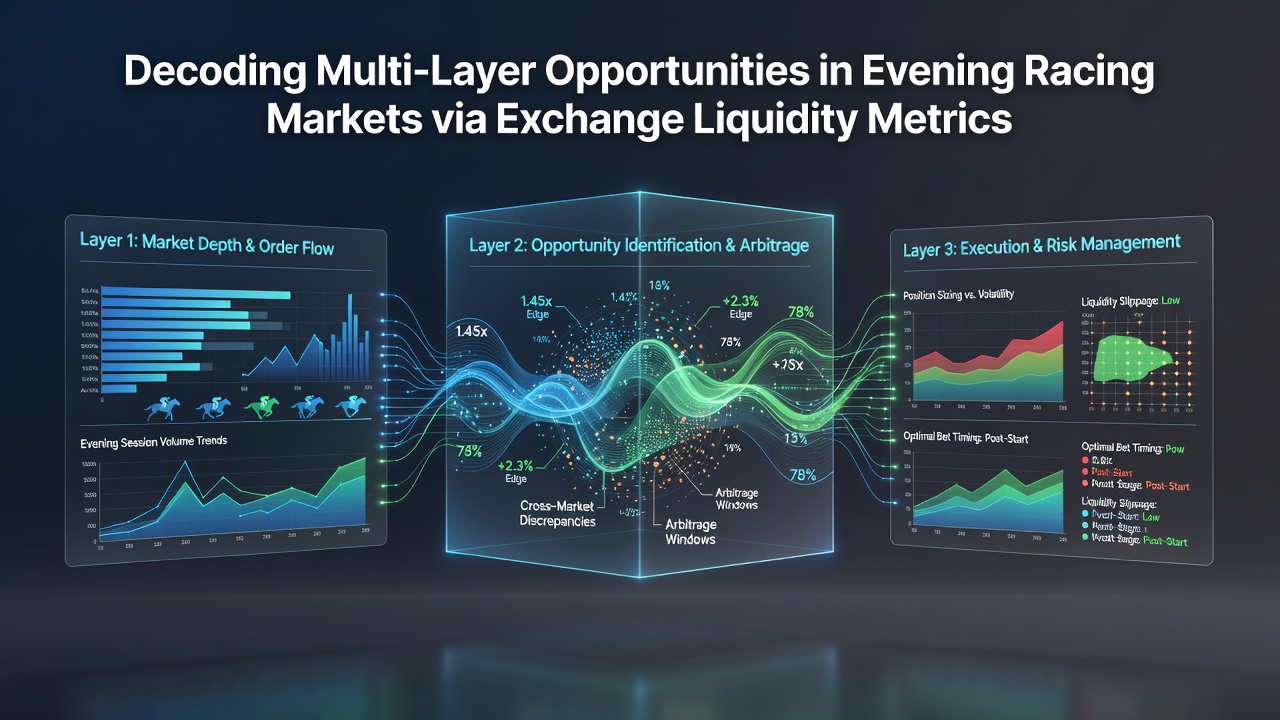
Market depth tools track available back and lay amounts at successive price points, allowing observers to identify when liquidity thins or thickens at specific odds levels, while volume spikes often signal shifts that create windows for position adjustments without requiring direct price prediction.
Core Liquidity Indicators in Evening Sessions
Researchers have documented how evening racing markets differ from daytime equivalents because participant numbers fluctuate more sharply after standard work hours, and this pattern produces measurable changes in available stakes at each tick; figures released by the Victorian Commission for Gambling and Liquor Regulation indicate that average depth in key Australian evening fixtures rose by double digits during the first half of 2026 compared with the prior year.
Order book imbalance ratios serve as one primary metric, calculated by dividing total back liquidity by total lay liquidity across a defined price range, and analysts note that readings above certain thresholds frequently precede rapid price movements when new orders arrive from larger accounts. Spread width between best back and best lay prices provides another signal, narrowing when market makers increase activity and widening when liquidity providers step away during quieter periods between races.
Multi-Layer Opportunity Mapping
Traders examine stacked liquidity bands to locate zones where small shifts in volume can trigger cascading order executions, and one documented approach involves marking price levels that hold at least three times the average stake seen in the preceding ten minutes. These bands function as temporary support or resistance points because incoming orders must overcome the visible depth before price advances or retreats further.
Studies conducted by the University of Sydney Business School on exchange data from 2025 and 2026 demonstrate that evening meetings generate higher clustering around mid-race updates, particularly when stewards release going changes or jockey reports that alter perceived probabilities. Observers track cumulative volume at each layer rather than single trades, because isolated large orders can distort short-term readings while sustained additions across multiple price points indicate genuine interest.
Timing Position Adjustments Using Depth Data
Position flips occur when participants move from back to lay or vice versa after liquidity patterns confirm a new equilibrium, and exchange platforms record these reversals through timestamped depth snapshots that show preceding order concentration. In July 2026, several European racing authorities reported elevated activity in twilight fixtures where liquidity maps helped identify exit points before final declarations altered market composition.
Participants often combine real-time depth feeds with historical evening session averages to filter noise, because isolated spikes without supporting volume at adjacent layers tend to revert quickly. Data aggregation services supply normalized metrics that account for field size and race distance, enabling consistent comparison across different meetings held on the same evening.
Regional Variations and Reporting Standards
North American tracks operating evening programs publish supplementary liquidity summaries through state gaming boards, and these disclosures allow cross-market analysis when exchange operators share anonymized order flow statistics. Australian and Canadian regulators have adopted similar transparency requirements in recent rule updates, producing comparable datasets that researchers use to study layer formation across time zones.
Industry associations such as the European Gaming and Betting Association compile periodic summaries of exchange activity in member states, highlighting how evening racing liquidity behaves under varying regulatory frameworks. These compilations show consistent patterns where deeper books appear in the hour before the first race and then redistribute as results accumulate.
Conclusion
Exchange liquidity metrics supply structured information that maps multi-layer opportunities in evening racing markets, and continued collection of depth and volume data across jurisdictions supports ongoing refinement of analytical approaches without reliance on outcome forecasting.